
Spots are filling quickly for 2027 AgVentures. Due to strong demand, we’re offering two opportunities to experience soybean harvest in Brazil and have added a new destination: Argentina.
For additional information or to reserve your spot, visit NoBullAg.com/AgVentures or reply to this message.

Week In Review
The Week in Under 60 Seconds
After continued strength heading into the U.S.–China meetings, markets took a decisive turn last week.
Monday’s highly anticipated tariff exemption list included several agricultural products, but soybeans were not among them, while the meetings themselves failed to produce any additional soybean purchase commitments. Corn, wheat, sorghum, cotton and other ag products made the list, but without firm commitments attached, the market was less than impressed with Washington’s so-called progress.
Adding insult to injury, Wednesday’s corn stocks surprise added enough cushion back to the new crop balance sheet that the path of least resistance suddenly turned lower.
China was on holiday all week, which helped explain some of the quieter trade, but the bigger issue was closer to home. Improving weather added harvest pressure, speculative length continued to head for the exits, and the market headed into the weekend staring down a week-long stretch of wide-open harvest weather.
Boom. Then bust.
Daily Play-by-Play
Monday: Markets started the week sharply lower as the U.S.–China tariff exemption list excluded soybeans and the meetings produced no new commodity-specific purchase commitments.
Tuesday: Beans bounced off Monday’s lows while continued western Corn Belt rain kept harvest slow, processor basis elevated and meal supplies tight.
Wednesday: USDA shocked the corn market with 2.095 bbu of September 1 stocks, sending December corn down more than 20 cents and pulling the broader grain complex lower.
Thursday: Markets stabilized somewhat, but long liquidation continued as improving harvest forecasts and China’s Golden Week shifted attention toward incoming bushels.
Friday: Another round of fund selling and a wide-open dry forecast pressured corn and beans, while soybean oil found support from sharply lower August stocks and record July biofuel demand.

Energies & Macro
Energy markets spent another week proving that headlines can matter just as much as the underlying fundamentals.
Key Takeaways
Brent and WTI went separate ways. WTI settled Friday at $91.11, down $1.30 or 1.4% on the week, while Brent finished at $102.25, essentially unchanged. That left Brent more than $11 over WTI — the widest since early May and well beyond the more normal $8–10 range. War-risk and freight costs continued to support waterborne Brent, while WTI had another problem: Washington.

Diesel was stuck in a game of policy ping-pong all week. President Trump said Wednesday that the administration was seriously considering a diesel export ban. Two days later, after the G7 agreed to release emergency diesel and crude stocks, he said the U.S. would not authorize one.

The back and forth left diesel trying to price two completely different outcomes in the span of a few days. November heating oil futures rallied roughly 20 cents in the first half of the week before giving all but 4 cents back by week’s end, while China’s decision to halt petroleum product exports for October added another reason for refined product markets to stay on edge.

The dollar kept grinding higher. The US Dollar Index closed at 101.93 Friday, up 0.95% on the week and marking a third straight weekly gain after touching 102.20 Thursday. Inflation is part of the reason: August PCE was still running 3.4% YoY, while the 10-year Treasury topped 5.30%, reaching a 24-year high earlier in the week. Friday’s weak 29,000 jobs print took some steam out of expectations for an October hike, but the dollar barely gave anything back.

Déjà vu at 102. Around this time two years ago, the dollar was sitting near 101.65 before beginning a move that eventually carried it above 110 by January. The initial push came from stronger U.S. data and a reset in Fed cut expectations. Then the election added fuel. After Trump’s November win, markets began pricing the potential inflationary impact of tariffs, tax cuts and stronger growth, which helped push Treasury yields and the dollar higher. This two-year chart puts the current move in perspective. Near-102 feels strong after three straight weekly gains, but we are still a far cry from the levels reached during that late-2024 run.

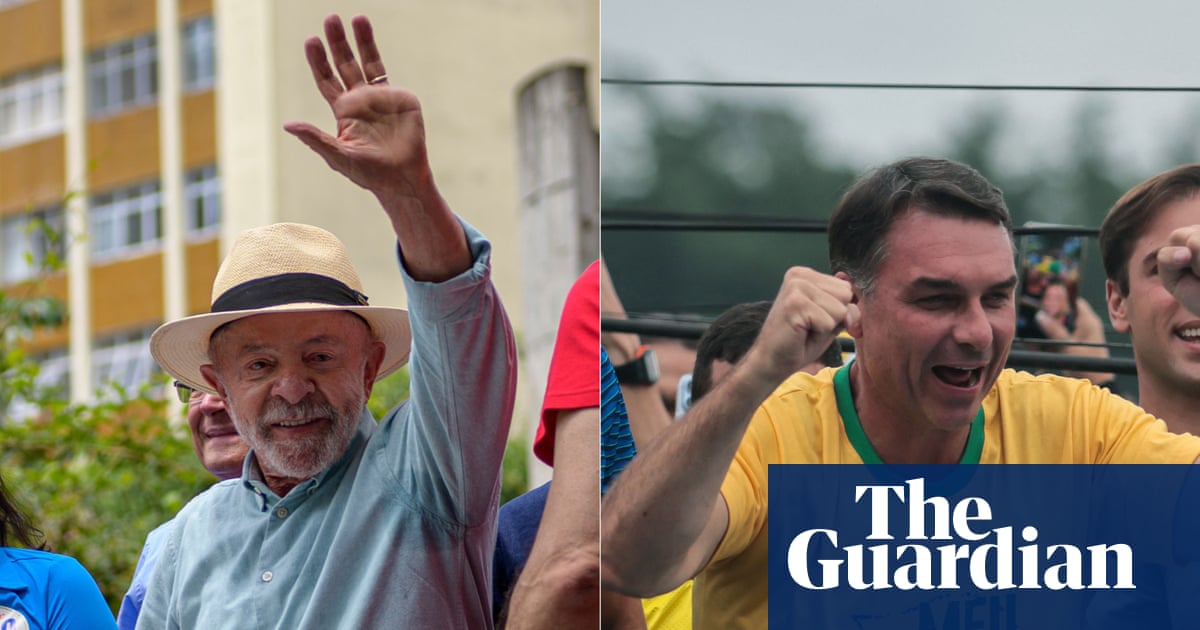
Speaking of elections, Brazil heads to the polls today. Lula and Flávio Bolsonaro are locked in a tight first-round race, with the latest CNT/MDA poll showing Lula at 43.1% and Bolsonaro at 38%. A runoff on October 25 remains likely if neither candidate clears 50%. For markets, the bigger issue is fiscal policy. Brazil’s high interest rates have helped support the real, but investors remain focused on government spending and debt regardless of who wins. That matters to ag because any meaningful move in the real can quickly change Brazilian farmer selling incentives and U.S. competitiveness.
Bottom Line: Energies & Macro
Last week was another reminder that markets are still stuck in a game of policy and headline ping-pong. Fundamentals matter and so do flows, but headlines can still hijack the market. The bigger question is what surprise is lurking around the next corner.
Soy Complex
The soy complex spent last week trading both the disappointment that followed the U.S.–China meetings and the transition from tight nearby supplies to a much more active harvest.
Key Takeaways
November beans suffered their largest weekly loss since late July. SX finished near $12.78, down more than 40 cents (-3.1%) on the week, with Monday’s China disappointment setting the tone before improving harvest prospects and the break in meal added even more pressure as the week wore on. By Friday, beans had traded down to $12.73 and cash markets were already starting to weaken as the market looked ahead to a much more active harvest window. For perspective, November 2025 futures were trading near $10.60 at this point last year — more than $2 below where SX sits today.

Meal was the real downside leader. December meal closed lower all five days last week, losing more than $23/ton (-6.3%) as the market began pricing the end of the western Corn Belt bean squeeze. Cash followed suit, with processor bids and nearby meal premiums weakening as crushers finally began to see better bean flows.

Mother Nature is finally going to let harvest get going. The next week is almost completely dry across the heart of the Corn Belt, including Iowa, the Dakotas, Nebraska, Minnesota, Illinois and Indiana. After weeks of delays, producers finally have a wide-open harvest window — one that should help bean deliveries improve and processors begin to ramp crush back up.
Keep reading with 14-days free trial
Subscribe to No Bull to keep reading this post and get 14 days of free access to the full post archives.
Start trial